The views expressed are those of Anchor Capital Advisors, LLC (“Anchor”) and are subject to change at any time. They are based on our proprietary research and general knowledge of said topic. The below content and applicable data are in support of our views on said topic. Please see additional disclosures at the end of this publication.
Summary
- Energy and policy drove the quarter. The war between the U.S. and Iran pushed oil and gas prices higher and added to inflation.
- The Fed, the European Central Bank, and the Bank of Japan all raised rates, the Fed for the first time since 2023. Long-term government bond yields in several major economies reached their highest levels in roughly two decades or more.
- Large-company stocks held up because earnings were strong. The main risk ahead is that heavy borrowing by the U.S. government and by companies building AI capacity pushes long-term yields higher without a stronger economy behind it.
- Bonds lost money this year, but they now start from higher income, which helps offset further price declines.
Overview – Global Capital Markets
Energy and the policy response to it shaped the third quarter. The war between the U.S. and Iran, which began in March 2026, passed its six-month mark with no settlement reached as of quarter end, and the preliminary agreement reached in June did not hold. Middle Eastern exports picked up late in the quarter, but much of the region’s supply is still disrupted, and damaged refineries and gas export plants will take a long time to repair. Oil prices rose sharply over the quarter, though they eased from their September highs. The sharpest pressure was in diesel, jet fuel, and natural gas, which feed more directly into transport costs and household energy bills.[1] Europe is especially exposed. No year in the fifteen-year data record has seen European gas storage this low heading into its heating season.[2]
Higher energy costs fed into inflation, and central banks moved in the same direction. The Federal Reserve’s September increase was its first since July 2023, and the European Central Bank, the Bank of Japan, and central banks in Australia, New Zealand, and Norway also tightened. In the U.S., core inflation is running around 3%. It has not been back at target in more than five years.[3] Most of the new pressure is coming from business costs, including energy, freight, tariffs, and shortages of AI-related components, and companies may pass more of those costs on to customers over time.[4] Even so, growth has been solid. Unemployment stayed low over the summer, and households kept spending as fuel costs rose.[5] Estimates for third-quarter growth are above the economy’s long-run pace. In our view, the Fed acted because inflation had stayed above target long enough to put its credibility at stake, and solid growth made that easier to do.
Chair Warsh has not signaled where rates are headed and has said he will judge whether policy is tight enough mainly from markets and lending conditions. For investors, that makes it less certain that the Fed would step in after a sharp market decline, as it often did after 2008.[6]
Long-term bond yields rose along with policy rates. Government yields in the U.S., the U.K., Germany, and Japan reached their highest levels in roughly two decades or more.[7] The U.S. 10-year Treasury yield ended the quarter above 5%.[8] Because the rise was global, U.S. government finances cannot be the whole explanation. Outside the U.S., higher energy costs and rate increases account for much of it. It is our opinion that within the U.S., the rise for most of the year reflected a stronger economy and a more active Fed rather than expectations of higher inflation ahead. That is why short-term yields rose more than long-term yields. Growth explains most of that rise, but the U.S. also has pressures of its own. Federal debt has passed $40 trillion.[9] AI-related corporate borrowing is competing with the Treasury for long-term capital. A five-year Treasury auction late in the quarter also drew unusually weak demand.[10]
Stocks held up better than rising yields alone would suggest because earnings were strong, led by AI-related companies. S&P 500 companies reported second-quarter profits more than 30% above a year earlier.[11] Valuations fell in most major markets as yields rose, but profit growth more than made up the difference. That is how rising yields usually play out when the economy is strengthening. Historically we’ve seen a rise driven by heavy borrowing works differently. Investors demand more pay to lend for long periods, and the rate used to value future profits goes up with nothing added to the profits themselves. The last week of September looked more like the second kind, with long-term yields rising much faster than short-term yields after the weak auction.[12] One week is not a trend, but it is the shift stock investors should watch most closely.
TABLE 1 – ASSET CLASS PERFORMANCE (As of September 30, 2026)

Source: FactSet financial data and analytics
U.S. Equities
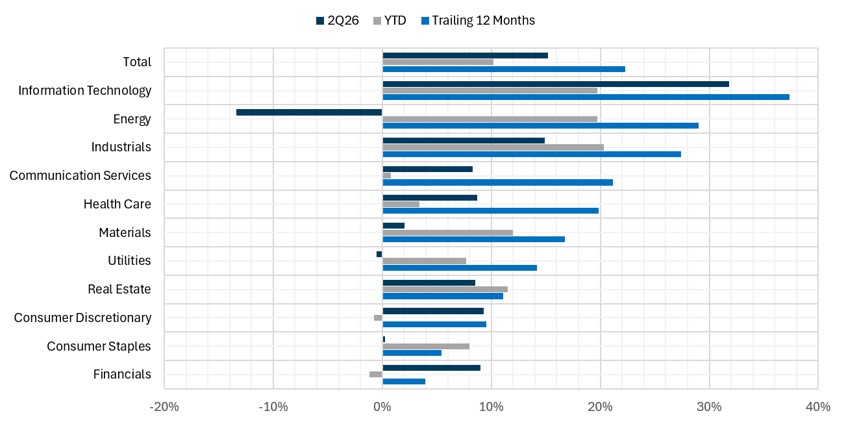
Gains showed up mainly in the headline index. The S&P 500 was close to its record high in late September, but a large share of stocks in the broader market had fallen well below their June levels.[13] Utilities and real estate, two of the most rate-sensitive sectors, fell during the quarter as yields rose. Semiconductor shares dropped almost 30% over a few weeks in the summer, even though analysts were raising their earnings estimates at the time.[14] Falling prices alongside rising estimates point to lower valuations rather than weaker business results, and higher rates explain part of that.[15]
Some of this year’s earnings strength came from higher selling prices. Memory chip prices rose sharply in 2026, which lifted semiconductor earnings.[16] Record diesel refining margins did the same for refiners.[17] Earnings growth has also spread along the AI supply chain. Spending by the large cloud providers now shows up in the results of the companies they buy from, particularly chipmakers, and semiconductors accounted for more than half of the S&P 500’s earnings growth in the most recent reported quarter.[18] Growth may slow next year even if it stays positive, since some of this year’s gains came from price increases that we think are unlikely to repeat at the same pace.
The AI buildout also met local resistance. Roughly $130 billion of data center projects were stopped or postponed in the first quarter of 2026, close to the total for all of 2025.[19] Even so, forecasts for next year’s AI spending were still rising at quarter end.[20] At this point, the resistance seems more likely to add cost and delay for builders than to reduce total spending.
The U.S. consumer is still spending, but unevenly. Households are putting more of their budgets toward health care, housing, and other necessities, with inflation-adjusted incomes roughly flat and savings near their lowest level of the cycle.[21] Housing shows the strain most clearly. Home prices have reached new highs even as mortgage rates rise, likely because owners with low fixed-rate mortgages are reluctant to sell, which keeps the supply of homes for sale tight.[22]
Higher rates affect some companies much more than others. Index valuations came down during the quarter, though they are not low by historical standards.[23] Modest rate-hiking cycles, those adding about 1.25 percentage points or less in total, have not usually hurt the S&P 500. Since 1962, it has been higher a year later more than 80% of the time.[24] The pressure falls on individual companies instead. Those with steady cash flow and modest debt are able to fund investment while more indebted competitors pay more to refinance. Smaller companies are more exposed. They led through August, but that reversed in September as long-term yields rose. Higher financing costs seem more likely to separate strong small companies from weak ones than to weigh on the group as a whole, which can make balance sheet quality more important in that part of the market.
TABLE 2 – S&P 500 SECTOR RETURNS (As of September 30, 2026)
Source: FactSet financial data and analytics
International Equities – Developed Markets & Emerging Markets
Non-U.S. equity markets have broadly kept pace with the U.S. market this year, though they lagged in the third quarter.[25] The dollar rose modestly this year, so those gains came against a currency headwind for U.S. investors. The energy shock has affected regions unevenly, however, which makes the differences between countries more important than the broad choice between U.S. and international exposure.
Developed Markets
Europe has absorbed the energy shock better than expected, with second-quarter growth beating forecasts.[26] Corporate earnings have done better still. Roughly two-thirds of European profits come from businesses that tend to benefit when inflation is higher, which has helped earnings grow even as energy costs climbed.[27] European households may feel more of the strain ahead. Eurozone inflation passed 3% during the quarter.[28] Fuel accounted for most of the increase, and budget negotiations and elections in several member states, including France, where deficits and debt are high, add political risk into 2027.[29] A cold winter is the main threat to both earnings and growth, given how little gas Europe has in storage.[30]
Japan’s market has been driven mainly by changes at home. Reforms are pushing companies to use their capital better and reward shareholders, and the return of moderate inflation after decades of flat prices has lifted sales and profits.[31] The Bank of Japan raised rates again in September, and Governor Ueda signaled that future increases could come faster.[32] Borrowing costs in Japan sat near zero for most of the period since the late 1990s, so how companies and households adjust to higher rates is an open question.
Emerging markets have been the strongest major region this year, though they slipped slightly in the third quarter.[33] Outside China, the forces behind those gains have differed sharply. In South Korea and Taiwan, the driver is AI. Both are major producers of the chips that AI depends on, and analysts lifted profit forecasts for both through July and August.[34] Much of the emerging market index’s gain this year has come from that same chip cycle, which also drives U.S. earnings. India’s market leans more on domestic banks and consumer companies, with less direct exposure to AI.[35] Its economy is growing strongly, but its stock market has lagged the region.[36]
Latin America depends more on commodities and interest rates than on technology, and the region’s stocks have outperformed most other markets since early 2025.[37] Higher energy prices help its commodity exporters. Brazil’s central bank began lowering rates again after a long hold at high levels.[38] Both supports would weaken if commodity prices fell or global rates rose further.
China is best treated separately. Household spending and private investment are weak, held back by falling property prices and efforts to pay down debt, while factories and exporters are doing well.[39] China has also handled the energy shock better than most large importers. Because it stockpiled oil before the war, it could buy much less crude while supply was tightest.[40] Neither advantage does much for Chinese households, however.
Interest Rates & Central Banks
The Fed described its September increase as removing “a dose of accommodation,” and Chair Warsh said the move “starts to show we are serious about this.”[41] Both phrases suggest the September increase may not be the last. Philadelphia Fed President Anna Paulson said late in the quarter that further increases may be needed.[42] Some forecasters think markets already expect more than the Fed will deliver.[43] Inflation data released at quarter end also came in softer than expected.[44] How long rates stay high matters more than how many more increases follow, because mortgage costs, corporate refinancing, and the value of long-lived assets depend on where rates sit over several years. Fed officials also raised their estimate of the long-run neutral rate, the level at which policy neither stimulates nor restrains the economy. That implies rates are unlikely to return to the levels of the past decade.
Short- and intermediate-term yields have risen faster than long-term yields this year as investors priced in a more active Fed. Long-term yields depend on more than the Fed, however. Large deficits and heavy borrowing to fund AI are likely to keep pressure on long-term yields whatever the Fed decides, so the cost of long-term borrowing may stay high even after the Fed stops raising rates. The counterargument is credibility. If investors come to believe the Fed has inflation under control, they may accept less extra yield to own long-term bonds.
Outside the U.S., the direction of policy is shared, but the pace is not. After two increases this year, the ECB has indicated a third is likely by December. German long-term yields reached two-decade highs along with other major markets, but rose less than most, which suggests the ECB’s early action helped. The Bank of England held rates steady, but its members made clear that a longer war could bring increases.[45] U.K. long-term yields rose sharply before the new government’s first budget.[46]
Currency
Our view last quarter was that the dollar was more likely to weaken than strengthen. That view rested on energy risk fading and on the Fed staying closer to hold than hike, though we identified a Fed more willing to raise rates as the main risk to it. Energy risk did not fade, and the Fed raised rates in September. The dollar has risen modestly this year, mostly in the first half. It firmed after the September rate increase but ended the third quarter close to where it began.[47]
The case for dollar support now rests on rate differentials, the gap between U.S. interest rates and rates elsewhere. When U.S. rates rise relative to others, and when yields after inflation rise alongside them, holding dollars pays more than it did before. Energy now works in the dollar’s favor as well. Earlier in the year, the ECB looked more likely than the Fed to respond to higher energy prices with rate increases, so energy spikes tended to help the euro. With the Fed now raising rates too, another energy spike is more likely to push U.S. rates higher and support the dollar.
Emerging market bonds have weathered this year’s jumps in oil prices and U.S. yields better than their size would suggest. Many of these countries offer high yields after inflation and have central banks with established credibility, and the dollar has not rallied sharply. In our view, a stable or slightly firmer dollar is manageable for these markets, while a sharp rise would remove one of the supports described above.
Fixed Income
Bonds offered more income this year than at almost any point in the past twenty years, yet broad bond indexes still lost money.[48] Rising yields do two things at once. They lower the price of bonds investors already own, and they raise the income available on new purchases. For a high-quality bond held to maturity, the starting yield is a reasonable estimate of the return, because price swings fade as the bond approaches repayment. A higher starting yield also provides more cushion, since yields would have to rise further before price losses outweighed a year of income.
Companies are paying very little extra to borrow compared with the government. Across most of the corporate bond market, that extra yield, known as the spread, was close to its lowest level in twenty years.[49] Most of a corporate bond’s income today comes from the level of interest rates, not from extra compensation for the borrower’s risk. Spreads have little room to narrow further, which can make the choice of individual borrowers more important.
AI borrowing has changed what investors own when they buy the corporate bond market, and that matters for diversification. In the first part of 2026, bond sales tied to AI infrastructure, chip financing, and data centers by highly rated (investment-grade) companies passed $300 billion, compared with $136 billion for all of 2025. Investors who hold corporate bonds as a counterweight to equities are increasingly holding the same underlying exposure in both places.[50]
Private credit warrants attention for a related reason. Most private loans carry floating rates, so a borrower’s interest cost rises as short-term rates rise. Higher rates reach those borrowers faster than they reach companies that locked in fixed-rate bonds several years ago. Views on what follows differ. Some argue that spreads this narrow offer little protection if results fall short, and that refinancing risk is concentrated in lending tied to AI.[51] The market has not been through a period of rising rates at its current size, and the available evidence does not settle the question. In our view, that uncertainty makes loan terms, borrower quality, and the choice of manager more important than usual.
Real Assets
Gold ended the quarter modestly higher, after a strong August rally that it largely gave back from late August through September as long-term yields rose.[52] The August rally came with heavy buying of gold-backed funds and a weaker dollar.[53] The later decline came as the dollar firmed and yields rose on expectations that the Fed would tighten further. Gold is often held as protection against inflation, but that appeal fades when bonds pay enough to stay ahead of expected inflation. Central banks have kept buying, led this year by Poland.[54] China has bought more since May.[55]
Real estate and infrastructure have a related role. Both are long-lived physical assets with contracted or lease-based revenue, which also makes them sensitive to interest rates, and both fell in the third quarter as yields rose. Established, income-producing real estate and infrastructure outside the data center and power buildout, along with government bonds and gold, are among the few holdings with little direct exposure to AI, which is why they can help diversify a portfolio against the AI cycle, though not against rising long-term rates.[56]
Outlook & Portfolio Positioning
Earnings look strong enough to support stocks if long-term interest rates level off near current levels. The larger risk is the one described at the start of this letter: long-term rates rising because of heavy borrowing rather than a stronger economy. This year, profit growth more than offset falling valuations. A borrowing-driven rise would add valuation pressure without stronger profits to offset it. Warning signs would include further weak Treasury auctions, long-term yields rising faster than short-term yields without stronger economic data, or resistance from bond or equity investors to companies raising money for AI capacity.
The second risk is energy, which runs both ways. A decline in oil prices would relieve pressure quickly. One estimate suggests oil falling back to its earlier-year range could undo a third to half of the recent rise in global bond yields.[57] Against that, European gas storage is unusually low heading into winter. The recent pickup in Middle Eastern exports may not last if shipping through the Strait of Hormuz becomes less secure. The third is AI. A slowdown in AI spending would hurt earnings but would also reduce the borrowing that competes for long-term capital, which would ease pressure on yields. Of the three, a borrowing-driven rise in yields is the hardest to diversify against, because it would hurt stocks and bonds at the same time. An AI slowdown, by contrast, would more likely hurt stocks while helping bonds.
Stock swings have historically grown larger in the weeks before midterm elections.[58] On average, stocks have recovered once the outcome became clearer, with post-election gains more than offsetting the pre-election decline, though not in every cycle. Over the past decade, staying invested through election cycles has produced better results than selling stocks whenever an investor’s preferred party was not in control.[59]
This quarter shifted where investment returns are coming from, toward earnings for stocks and income for bonds. That puts more weight on the quality of individual holdings: companies that can fund themselves without leaning on debt, bonds that offer enough extra yield for the chance of default, and diversifiers whose returns do not hinge on the AI cycle. The gap between the index and the typical stock has also left many individual companies less expensive than the index itself.[60] Energy, long-term rates, and AI financing are unlikely to settle quickly, which argues for portfolios that do not depend on getting any one of them right.